We use cookies to improve your experience on our site, analyze site traffic, and assist in our marketing efforts. By clicking "Accept all," you agree to the storing of cookies on your device. You can choose to "Reject all" non-essential cookies. For more information, please read our Cookie Policy.
Gazumping UK 2026: Is It Legal and How to Avoid It
A complete 2026 guide to gazumping for UK home buyers and sellers: definition, legality, gazundering, costs, the June 2026 reform roadmap and how an early survey cuts the risk.
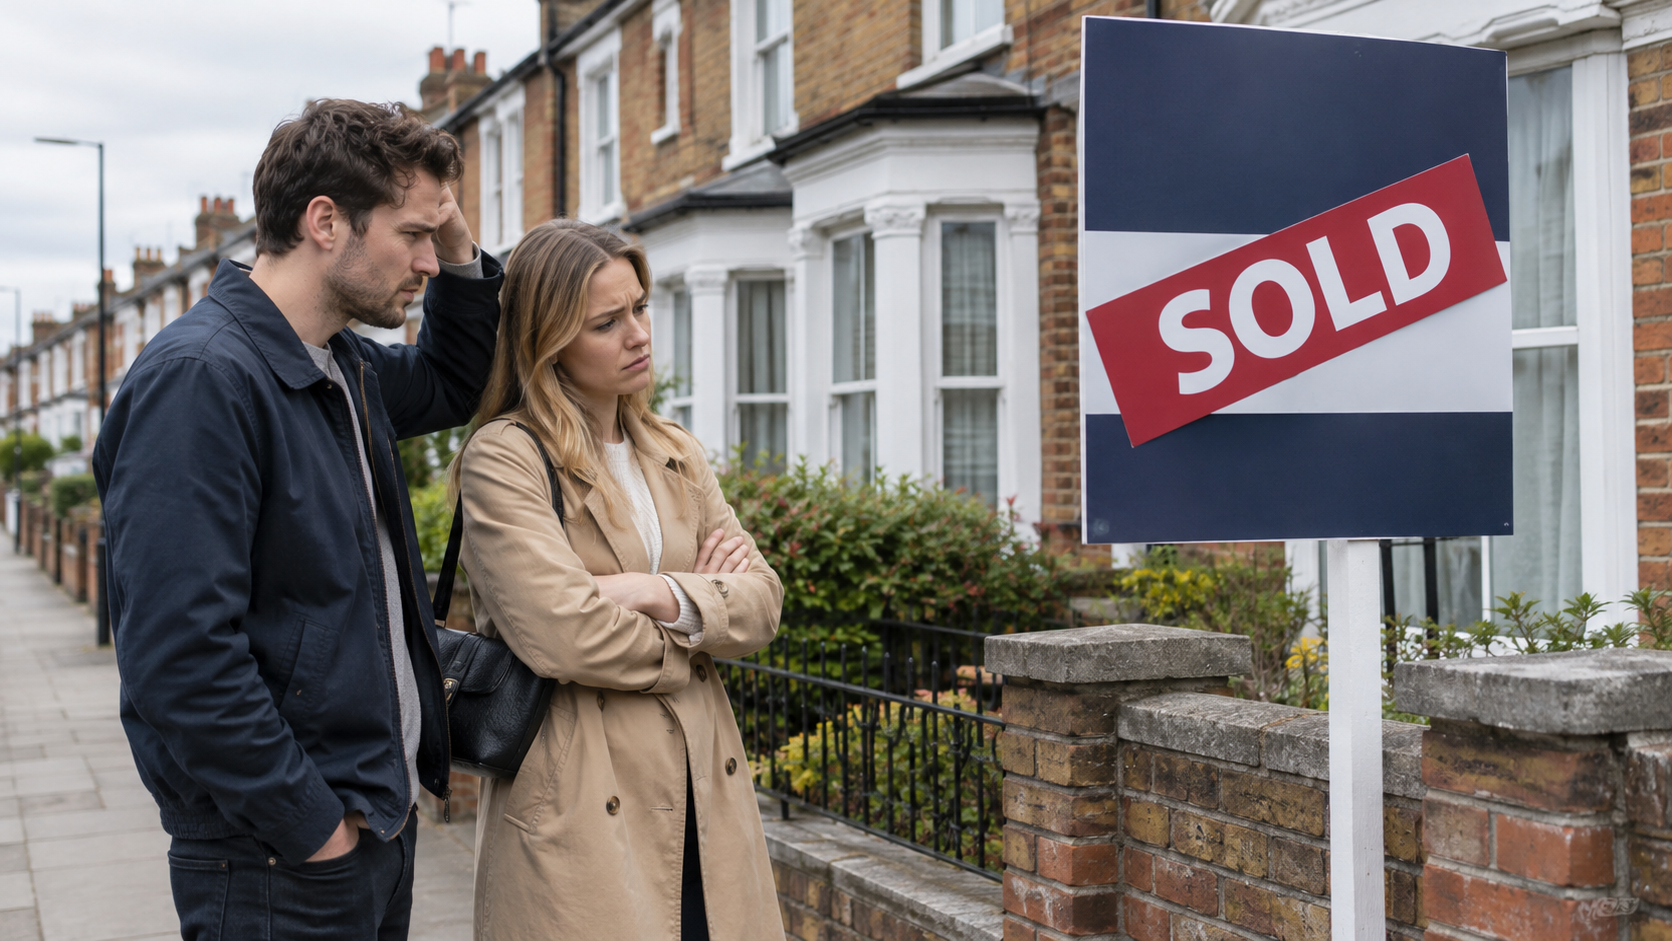
Gazumping is one of the most frustrating things that can happen to a home buyer in England and Wales. You have had an offer accepted, paid for searches, instructed a solicitor and perhaps booked a survey – and then the seller accepts a higher offer from someone else. In 2026 the practice is still perfectly legal, but the rules are finally changing. This guide explains what gazumping is, how often it happens, what it costs, and the practical steps that give you the best chance of getting to exchange of contracts with your purchase intact.
Key takeaways
Gazumping is when a seller accepts a higher (or better) offer from another buyer after already accepting yours, before contracts are exchanged.
It is legal in England, Wales and Northern Ireland because an accepted offer is not binding until written contracts are exchanged under section 2 of the Law of Property (Miscellaneous Provisions) Act 1989.
The Government’s June 2026 Home Buying and Selling Reform Roadmap confirms plans for binding conditional contracts, with penalties for parties who pull out without good reason – but legislation is still some way off.
Around one in three transactions currently fall through, costing consumers roughly £400 million a year according to MHCLG.
The fastest protection is speed: get your mortgage, legal work and survey moving in the first fortnight after your offer is accepted.
A quick, early survey from a suitably qualified, accredited surveyor shortens the gap between offer and exchange and gives you evidence to negotiate rather than walk away.
Gazumping leaves buyers out of pocket for surveys, searches and legal fees, with no home to show for it.
What is gazumping?
Gazumping is when a seller who has already accepted your offer on a property then accepts a higher offer from a different buyer before contracts are exchanged. Because the sale is not legally binding until exchange, the seller can withdraw without penalty, leaving the original buyer with lost fees and no home.
The word dates back to the 1970s property boom and has been part of the British home-buying vocabulary ever since. Gazumping does not always involve a higher price. A seller may also switch to a buyer who is chain-free, has a mortgage ready, or can complete more quickly – the common thread is that the seller abandons an agreed deal for a better one after you have started spending money.
If you are at the offer stage, our guide to making an offer on a house explains how to structure an offer that sellers are less likely to abandon.
Is gazumping legal in the UK?
Yes. In England, Wales and Northern Ireland, gazumping is legal. Under section 2 of the Law of Property (Miscellaneous Provisions) Act 1989, a contract for the sale of land must be made in writing, contain all the agreed terms and be signed by both parties. A verbal agreement, an email from the estate agent or a “sold subject to contract” board does not meet that test. Until contracts are formally exchanged, either side can walk away for any reason.
Estate agents are also under a legal duty to pass on every offer they receive to the seller, even after a sale has been agreed, unless the seller has instructed them in writing not to. That is why a rival buyer can still get their higher offer in front of the seller weeks after yours was accepted.
Scotland is different
In Scotland the system works differently. Once the buyer’s and seller’s solicitors have concluded missives (the exchange of formal letters that make up the contract), the deal is binding, and that typically happens much earlier in the process. Gazumping is therefore far less common north of the border, and the Law Society of Scotland’s professional rules discourage solicitors from acting for a seller who tries to gazump.
Gazumping vs gazundering: what is the difference?
Gazundering is the mirror image of gazumping. Here the buyer reduces their offer at the last moment, usually just before exchange, when the seller is under pressure to complete and may feel forced to accept. Like gazumping, it is legal until exchange. A buyer who lowers their offer because a survey has uncovered a defect is renegotiating on evidence, which is normal and reasonable. A buyer who cuts the price the day before exchange with no new information is gazundering.
Gazumping is driven by the seller; gazundering is driven by the buyer. Both are legal in England and Wales until exchange of contracts.
Term
Who does it
What happens
When it happens
Legal?
Gazumping
Seller
Accepts a higher or better offer after agreeing yours
Between offer acceptance and exchange
Yes (England, Wales, NI)
Gazundering
Buyer
Lowers the agreed price shortly before exchange
Usually days before exchange
Yes (England, Wales, NI)
Gazanging
Seller
Withdraws from the sale altogether and stays put
Any time before exchange
Yes (England, Wales, NI)
Renegotiation after survey
Buyer
Reduces offer to reflect defects found by a surveyor
After the survey report
Yes, and widely accepted
How common is gazumping in 2026?
There is no single official gazumping statistic, but the wider picture on failed sales is well documented. The Ministry of Housing, Communities and Local Government’s Home Buying and Selling Reform Roadmap, published on 19 June 2026, states that around one in three transactions fall through, that the average journey from offer to completion is around 120 days (about 60% longer than in 2007), and that fall-throughs cost consumers roughly £400 million a year. Santander research cited in the same document puts the cost to the wider economy at around £1.5 billion a year.
Industry trackers paint a similar picture for 2026. Quick Move Now’s quarterly data put the national fall-through rate at 23.7% of agreed sales in the first quarter of 2026, and TwentyCi’s Q2 2026 Property & Homemover Report found that 23.4% of listings had suffered at least one fall-through so far this year, an improvement on 24.4% a year earlier. In Quick Move Now’s Q2 2026 breakdown, the leading causes were a buyer’s mortgage being refused (33%), survey issues (27%), and chain breaks, changes in buyer circumstances and legal issues (13% each).
Gazumping itself tends to spike in hot markets where several buyers chase each property, and fade when the market cools. With UK house price growth slowing through the autumn of 2026 and buyers enjoying more choice, outright gazumping is less common than during the 2021 boom – but a long, slow transaction still leaves you exposed, and the long gap between offer and exchange is exactly when a rival buyer can appear.
What does gazumping cost the buyer?
When a purchase collapses, the buyer loses whatever they have already spent. Typical unrecoverable costs include conveyancing work to date, local authority and other searches, the mortgage valuation or arrangement fee, and the survey. Industry estimates commonly put the loss at around £2,700 per failed transaction, and it can be considerably more on a higher-value purchase or where a full building survey has been commissioned.
Cost typically lost when gazumped
Typical range (England & Wales, 2026)
Conveyancing fees for work completed
£300 – £1,000+
Local authority, drainage and environmental searches
£250 – £450
Mortgage valuation or product fee
£0 – £1,000+ (some lenders refund if the loan does not proceed)
RICS Level 2 HomeBuyer survey
£400 – £900
RICS Level 3 building survey
£600 – £1,500+
Home buyer’s protection insurance (optional, refunds some of the above)
You cannot make gazumping illegal, but you can make it far less likely by removing the two things that tempt sellers to switch: time and uncertainty.
Ask for the property to be taken off the market. Make it a condition of your offer that the seller withdraws the listing from Rightmove, Zoopla and the agent’s own site and stops viewings. Get the agent’s confirmation in writing.
Have a mortgage agreement in principle before you offer. Sellers favour buyers who are demonstrably able to proceed. A decision in principle, proof of deposit and a solicitor already instructed all signal that you will not cause delays.
Instruct your solicitor and surveyor on day one. Every week of delay is a week in which a rival buyer can appear. Book your building survey as soon as the offer is accepted rather than waiting for the mortgage valuation.
Propose a lock-out (exclusivity) agreement. This is a short written agreement in which the seller promises not to negotiate with anyone else for a fixed period, typically two to four weeks, while you progress to exchange. It does not force the seller to sell, but breaching it can give you a claim for your wasted costs.
Consider a reservation agreement. The Government’s 2026 roadmap encourages voluntary use of reservation agreements, under which both parties pay a deposit that is forfeited if they withdraw without a legitimate reason. Ask the agent whether the seller will sign one.
Agree a timetable. Fix target dates for the survey, mortgage offer, enquiries and exchange, and share them with both solicitors and the agent. Our home buying timeline explains what a realistic schedule looks like.
Keep communicating. A seller who hears from you (via the agent) every week is far less likely to entertain another buyer than one left in silence.
Build a relationship with the seller. Where possible, meet the seller at the viewing. People are less willing to gazump someone they know and like.
Take out home buyer’s protection insurance. For a modest premium these policies refund a proportion of conveyancing, survey and mortgage fees if the purchase falls through due to gazumping.
Be ready to exchange early. If both sides are ready, exchange with a longer completion date rather than waiting. Once exchanged, the seller cannot gazump you.
Why an early survey is your best defence
Surveys sit at the centre of the gazumping problem for two reasons. First, the survey is often the single largest cost a buyer loses when gazumped. Second, and more importantly, survey delays are one of the main reasons the offer-to-exchange period stretches to two or three months, giving rival buyers time to intervene.
Booking a survey immediately after your offer is accepted does three things. It compresses the timeline, because your solicitor can raise enquiries on the findings while the mortgage application is still in progress. It gives you an evidence-based position if you need to renegotiate – see our guide on how to negotiate the house price after your survey – so that any price reduction is justified rather than looking like gazundering. And it tells the seller and agent that you are a serious, proceedable buyer.
Not sure which level of survey you need? Read HomeBuyer report vs building survey. Always use a suitably qualified, accredited surveyor, regulated by a recognised body such as RICS, CIOB or RPSA, so that your report is accepted by lenders and solicitors without question.
An early survey from a suitably qualified, accredited surveyor shortens the time you are exposed to gazumping and gives you facts to negotiate with.
What to do if you have been gazumped
Being gazumped is upsetting, but you have options.
Find out exactly what the rival offer is. Ask the agent whether the new buyer is offering more money, a faster timescale or a chain-free position. You may be able to match the terms that matter most to the seller without paying more.
Decide your ceiling before you respond. Do not get drawn into a bidding war that takes you beyond what the property is worth. If you are unsure of value, an independent RICS Red Book valuation gives you an objective figure.
Use your survey as leverage. If your survey has already identified defects, the seller knows the new buyer’s survey will find the same issues and may well renegotiate. A buyer with a completed survey who can exchange quickly is often more attractive than a higher bidder starting from scratch.
Claim on your insurance. If you took out home buyer’s protection, notify the insurer promptly.
Check any lock-out agreement. If the seller signed one and breached it, speak to your solicitor about recovering wasted costs.
Be prepared to walk away. Sales agreed with gazumpers fall through too. Ask the agent to keep you informed in case the new deal collapses.
Will gazumping be banned? The 2026 reforms explained
The Government consulted on reform of the home buying and selling process between 6 October and 29 December 2025, receiving 1,133 responses. Its Home Buying and Selling Reform Roadmap, published on 19 June 2026, sets out a multi-year programme that directly targets gazumping and gazundering.
Binding conditional contracts. 72% of respondents supported making agreements more binding. The roadmap commits to working with industry during 2026 to prepare for binding contracts, defining a penalty fee structure in 2027–28, and legislating later in this Parliament when parliamentary time allows. Penalties would reflect the stage at which a deal collapses, with listed exceptions (58% of respondents backed exceptions such as death or serious illness, newly discovered information and major financial change).
Mandatory upfront information. 79% of respondents supported requiring sellers to provide a “sales pack” before listing, including searches and a condition report. Guidance on voluntary sales packs is due in 2026, with legislation to follow. Binding contracts will only come into force once sales packs are embedded, because buyers cannot safely commit before they have full information about the property.
Reservation agreements. During 2026 the Government will promote voluntary reservation agreements as an interim protection.
Estate agent regulation. A non-statutory Code of Practice is due in 2026, followed by consultation on mandatory qualifications in 2027–28.
Digital transactions. Digital ID, electronic signatures and digital property logbooks are being rolled out to cut the 120-day average transaction time.
In short, gazumping is not banned yet, and it will not be for at least a couple of years. Until binding contracts arrive, the protections in this guide remain essential. We track the reform programme in our coverage of the home buying and selling reform roadmap and upfront property information.
Advice for sellers: should you gazump?
Sellers sometimes receive a genuinely higher offer after agreeing a sale. Before accepting it, weigh the risks. The new buyer may not have a mortgage in place, may be in a chain, or may reduce their offer once their own survey reports the same defects your first buyer already knew about. Fall-through data shows that a third of failed sales collapse because the buyer’s mortgage is refused. A proceedable buyer who has already instructed a surveyor and solicitor is frequently worth more than a higher headline figure from someone who has yet to start. If you do consider switching, give the original buyer the chance to match the terms first; it is fairer and often faster.
Why choose Survey Merchant for your pre-purchase survey?
The single most effective thing you can do to reduce the risk of gazumping is to move quickly and decisively once your offer is accepted. Survey Merchant is built for exactly that.
Accredited surveyors matched to your property. Our panel includes suitably qualified surveyors regulated or accredited by bodies such as RICS, CIOB and RPSA, so you get the right expertise for a Victorian terrace, a 1930s semi or a new-build flat.
Nationwide UK coverage with local knowledge. Wherever you are buying, we match you with a surveyor who knows the local housing stock and its typical defects.
Fast turnaround. Early inspection dates and prompt reporting shorten the gap between offer and exchange – the window in which gazumping happens.
Transparent, competitive fixed fees. You know the cost before you commit, which matters when you are budgeting for a purchase that could still fall through.
Impartial advice. Our surveyors work for you, not the seller or the lender, so the report gives you honest evidence to negotiate with.
End-to-end support. From choosing between a Level 2 and Level 3 survey to understanding the findings and, if needed, an independent valuation, we support you through to exchange.
Gazumping is when a seller accepts a higher or better offer from another buyer after already accepting yours, but before contracts have been exchanged. The original buyer loses the property and any money spent on surveys, searches and legal work.
Is gazumping illegal in the UK?
No. In England, Wales and Northern Ireland an accepted offer is not binding until written contracts are exchanged, so a seller can legally accept another offer at any point before then. In Scotland the deal becomes binding once missives are concluded, which happens much earlier, so gazumping is rare there.
What is the difference between gazumping and gazundering?
Gazumping is done by the seller, who switches to a higher offer after agreeing yours. Gazundering is done by the buyer, who lowers their offer shortly before exchange. Reducing an offer because a survey has found defects is normal renegotiation, not gazundering.
How can I stop myself being gazumped?
Ask for the property to be taken off the market, have a mortgage agreement in principle, instruct your solicitor and surveyor immediately, propose a lock-out or reservation agreement, agree a timetable, keep in regular contact and consider home buyer protection insurance. The quicker you reach exchange, the smaller the window for gazumping.
Is the Government banning gazumping?
Not yet. The Home Buying and Selling Reform Roadmap published on 19 June 2026 commits to introducing binding conditional contracts with penalties for withdrawing without good reason, but legislation will come later in this Parliament and only once mandatory upfront sales packs are in place. Voluntary reservation agreements are being promoted in the meantime.
What can I do if I have been gazumped?
Find out what the rival offer actually is, decide your maximum price in advance, use your completed survey and readiness to exchange as leverage, claim on any home buyer protection insurance, check whether a lock-out agreement was breached, and be prepared to walk away. Sales to gazumpers often fall through, so ask the agent to keep you informed.