We use cookies to improve your experience on our site, analyze site traffic, and assist in our marketing efforts. By clicking "Accept all," you agree to the storing of cookies on your device. You can choose to "Reject all" non-essential cookies. For more information, please read our Cookie Policy.
Bank of England Holds Base Rate at 4% September 17 2026: What It Means for UK Property Buyers and Surveyors
The MPC held Bank Rate at 4.00% on 17 September 2026. Mortgage pricing near 4.38% for best 5-year fixes, house prices flatten across Halifax, Nationwide and Zoopla, and RICS data shows stabilisation as surveyor demand holds steady.
The Bank of England held Bank Rate at 4.00% on 17 September 2026. For UK property buyers, this means mortgage costs stay broadly where they have been for months, with the best five-year fixed rates sitting around 4.38%. Surveyors, meanwhile, are seeing steadier but still cautious demand as buyers weigh borrowing costs against long-term value.
Key Takeaways
The MPC voted to hold Bank Rate at 4.00% on 17 September 2026, keeping borrowing costs unchanged.
Best five-year fixed mortgage rates sit around 4.38% in September 2026; tracker deals track the base rate plus lender margin.
Halifax puts the average UK house price at £306,000, Nationwide at £278,500, and Zoopla at £272,800 - the gap reflects different measurement methods.
The RICS August 2026 survey shows new buyer enquiries at -19% and agreed sales at -17%, signalling stabilisation rather than a downturn.
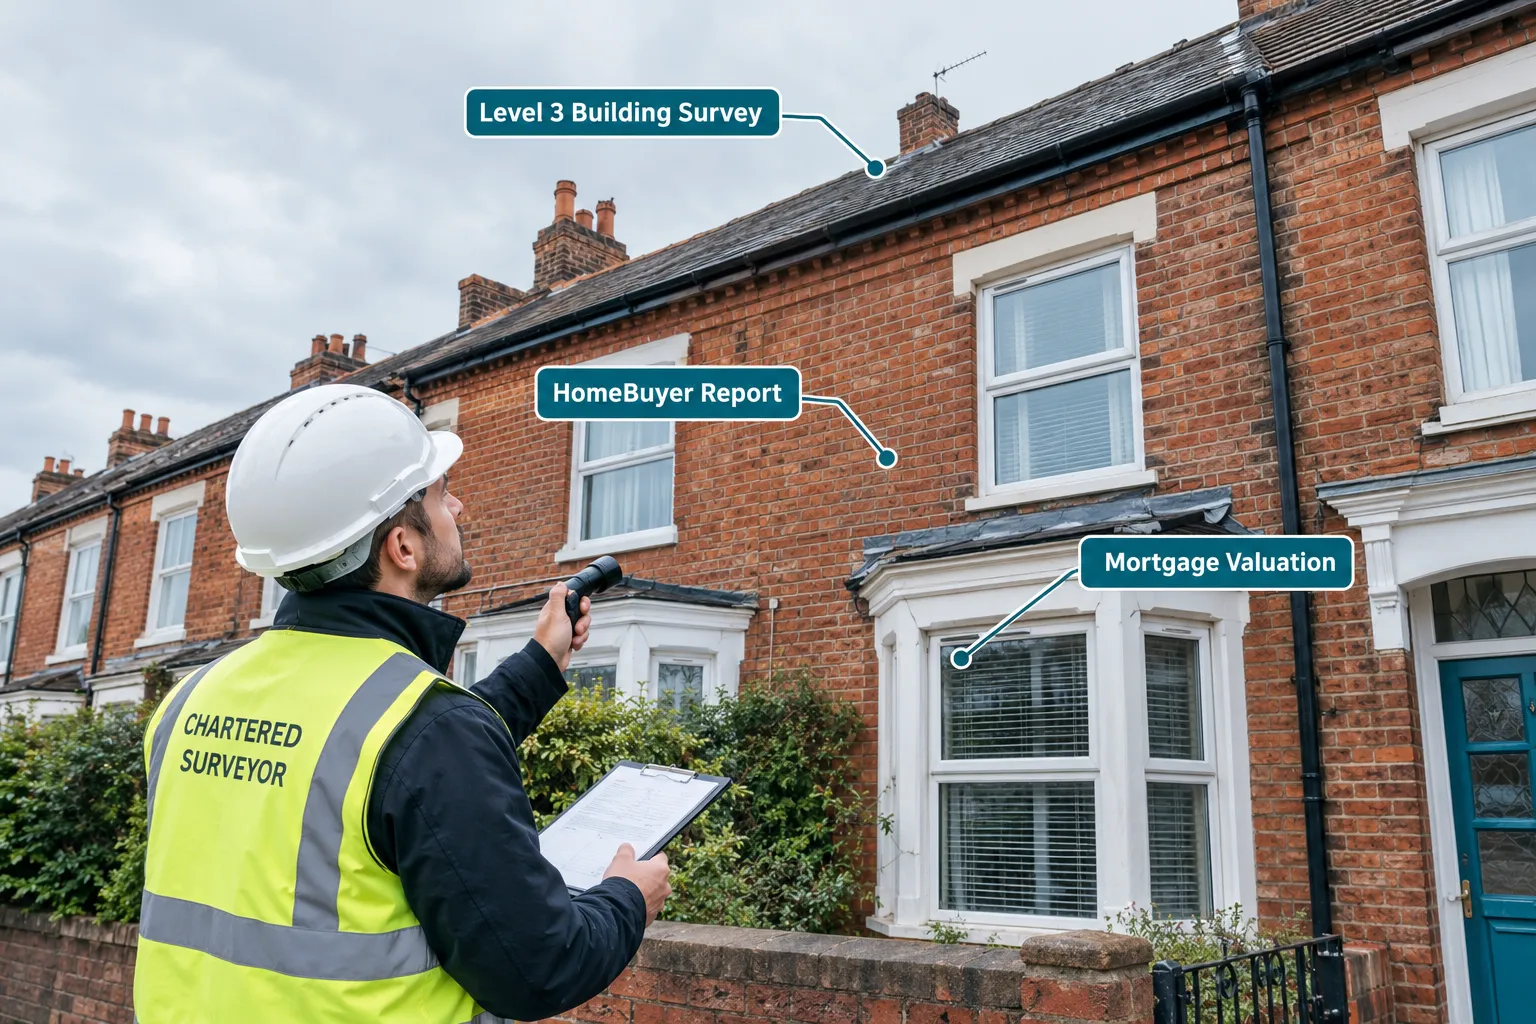
Surveyors are reporting steady demand for Level 3 Building Surveys, HomeBuyer Reports and mortgage valuations as buyers seek certainty before committing at 4% borrowing costs.
Homeowners coming off 2021-era fixed deals face the sharpest payment increases and should start remortgaging conversations three to six months before their deal ends.
Bank of England Holds Base Rate at 4% on 17 September 2026: The MPC Decision
The Monetary Policy Committee voted to hold Bank Rate at 4.00% on 17 September 2026, choosing continuity over further tightening. This is the clearest signal yet that the Bank sees 4% as roughly where policy needs to sit for now, rather than a stepping stone to something higher.
The MPC held Bank Rate at 4.00% at its 17 September 2026 meeting.
Bank Rate had been held at 3.75% across several consecutive meetings earlier in 2026 as the Committee weighed inflation risks against a fragile economy. Inflation fears mounted through the summer, and today's hold reflects a Committee still cautious about cutting too soon, even as some members argue the economy needs relief.
Decision rule: if you are waiting for the Bank's own commentary to signal cheaper mortgages, note that a hold at 4% is a statement of caution, not a promise of future cuts.
What the Bank of England Base Rate Means for Mortgage Rates
The base rate is the interest rate the Bank of England charges commercial banks, and it acts as the anchor for nearly all UK mortgage pricing, from tracker deals to new fixed-rate products. When Bank Rate sits at 4.00%, lenders build their margins, funding costs and profit expectations on top of that figure to set the rates borrowers actually pay.
Base Rate vs Mortgage Rate: The Difference
Tracker mortgages move in near-lockstep with Bank Rate, typically at base rate plus a fixed margin.
Fixed-rate mortgages are priced off swap rates, which reflect where markets expect rates to go over the fix's term.
Standard variable rates (SVRs) sit well above base rate and are the most expensive option for most borrowers.
Current Fixed and Tracker Mortgage Rates in September 2026
Best-buy five-year fixed mortgages are pricing around 4.38% in September 2026, a level that has held fairly steady since the base rate settled at 4.00%. Two-year fixes and tracker products sit close behind, generally within half a percentage point either way depending on deposit size and lender appetite.
A mortgage at 4.00% base-rate-linked pricing costs noticeably more than the sub-2% deals common in 2021. On a £250,000 repayment mortgage over 25 years, moving from a 2% rate to a 4.4% rate adds roughly £330 to £380 to the monthly payment.
How a 4% Base Rate Affects UK House Prices
A held base rate at 4% keeps mortgage affordability roughly stable, which supports gentle price movements rather than sharp swings in either direction. The three main UK house price indices currently sit at different levels because they measure different things: Halifax reports an average price of £306,000, Nationwide reports £278,500, and Zoopla puts its market estimate at £272,800.
Common mistake: treating one index as the national average. Each provider samples a different slice of the market - Halifax and Nationwide skew towards their own mortgage customers, while Zoopla covers a wider valuation base including cash buyers. Compare trend direction across indices, not absolute figures.
RICS August 2026 Survey: Signs of Market Stabilisation
The RICS residential survey for August 2026 shows new buyer enquiries at a net balance of -19% and agreed sales at -17%. A net balance below zero still means most respondents saw flat or falling activity, but the pace of decline has slowed compared with earlier in the cycle - the fifth improvement in a row.
Buyer enquiries softening at -19% suggests hesitancy tied to the 4% rate environment, not a full retreat.
Sales at -17% point to transactions still completing, just at a slower rhythm.
Surveyors report price expectations flattening across most UK regions.
How Surveyors Price Properties When Rates Are High
Surveyors do not set prices; they assess evidence of value using comparable sales, condition, and local market activity. Higher interest rates influence that evidence indirectly by slowing transaction volumes and softening buyer competition. When fewer deals go through, surveyors lean more heavily on recent sold prices, adjusted for condition and any signs of price reductions during marketing.
Surveyor demand for Level 3, HomeBuyer and Mortgage Valuation reports is holding steady in September 2026.
Surveyor Demand: Level 3, HomeBuyer and Valuations
Demand for detailed surveys is rising relative to basic valuations because buyers borrowing at 4% want fewer surprises after completion:
Report type
Best suited to
Why demand is holding
Level 3 Building Survey
Older, period, or altered properties
Buyers want full structural clarity before committing at higher borrowing costs
HomeBuyer Report (Level 2)
Conventional, reasonably modern homes
Balances cost and detail for straightforward purchases
Mortgage Valuation
Lender requirement on all mortgaged purchases
Confirms security value for the loan, unaffected by rate holds
Survey Merchant's Valuation, HomeBuyer Report and Level 3 Building Survey services are seeing consistent enquiry volumes through September 2026, reflecting buyers who would rather pay a few hundred pounds for certainty than risk an expensive repair bill on top of a 4% mortgage.
Remortgagers: What Happens When 2021 Fixed Deals Roll Off
Borrowers coming off five-year fixed deals taken out in 2021, when many rates sat between 1.5% and 2.5%, face the steepest payment jump of any group in this cycle. Moving onto a 4.00 - 4.5% product roughly doubles the interest portion of a typical monthly payment.
Is Now a Good Time to Refinance at a 4% Base Rate?
Refinancing now is generally sensible for anyone whose current deal is ending within the next six months. Waiting rarely produces a materially cheaper rate while risking a costly move onto a lender's standard variable rate. Locking a new deal three to six months ahead, using a rate-lock or reservation feature where available, protects against any further tightening without forcing a decision too early.
Check exit fees and early repayment charges before switching lenders.
Compare a straight product transfer with your existing lender against a full remortgage - transfers are often faster and cheaper.
Get a fresh valuation early if your loan-to-value has shifted, since a lower LTV band can unlock a meaningfully better rate.
Should You Buy Property Now or Wait for Rate Cuts?
Buying now suits anyone financially ready and planning to stay put for five-plus years, because a held 4% rate offers pricing stability that waiting does not guarantee to improve. Choose to wait only if affordability is genuinely marginal, since a small future rate cut is unlikely to offset the risk of house prices firming further while you sit out.
First-Time Buyers When Base Rate Stays at 4%
First-time buyers face tighter affordability calculations at 4%, since lender stress tests apply a further margin above the actual mortgage rate. A held rate at least removes the risk of sudden further tightening mid-application, giving first-time buyers a stable target to plan deposits and Agreement in Principle timing around.
Focus on maximising deposit size to access better loan-to-value bands.
Get pre-approved before house-hunting seriously.
Budget a HomeBuyer Report or Level 3 survey into upfront costs rather than skipping it to save a few hundred pounds.
Practical Guidance for Buyers, Sellers and Remortgagers
Buyers: get an Agreement in Principle before viewing seriously, and budget for a Level 3 Building Survey on any period property.
Sellers: price realistically against local sold comparables, not last year's asking prices, given the -17% RICS sales balance.
Remortgagers: start the process three to six months before your current deal ends.
Investors: stress-test yields at 5%-plus and treat the current hold as a stable but not permanent baseline.
Everyone: book a valuation or survey early - surveyor capacity tightens as the autumn market picks up.
FAQ
What is the Bank of England base rate as of 17 September 2026? Bank Rate stands at 4.00% following the MPC's decision to hold on 17 September 2026.
How does the base rate affect my mortgage? Tracker mortgages move directly with base rate changes, while fixed-rate mortgages are priced off swap rates that reflect where markets expect rates to head over the fix's term.
Will mortgage rates fall before the end of 2026? Possibly, but not guaranteed. The MPC's decision to hold rather than cut on 17 September 2026 suggests no imminent reduction in Bank Rate.
Do I need a survey when remortgaging? Lenders require a mortgage valuation, but an independent HomeBuyer Report or Level 3 Building Survey gives homeowners their own view of the property's condition, which a lender's valuation does not provide.
Conclusion
The Bank of England's decision to hold Bank Rate at 4.00% on 17 September 2026 gives the UK property market a period of relative stability rather than a fresh shock in either direction. Mortgage pricing around 4.38% for best five-year fixes, house price benchmarks from Halifax, Nationwide and Zoopla sitting within a fairly tight range, and RICS data pointing to stabilising rather than collapsing activity all tell the same story: a market adjusting to higher borrowing costs, not one in crisis.
Buyers ready to proceed should move forward with realistic budgeting rather than waiting on a rate cut that has not been confirmed. Sellers should price against current comparables, not last year's market. Remortgagers coming off cheaper 2021 deals need to start the refinancing conversation now, and anyone buying should build a Level 3 Building Survey, HomeBuyer Report or Valuation into their plans early, before autumn demand tightens surveyor availability.